


The landscape of US spectrum auctions is shifting as the Federal Communications Commission moves to rebuild its auction pipeline and the wireless industry intensifies its push for access to the 4 GHz band. A recent conversation between FCC Chairman Brendan Carr and CTIA President and CEO Ajit Pai offered the clearest picture yet of what lies ahead for spectrum allocation in the United States.
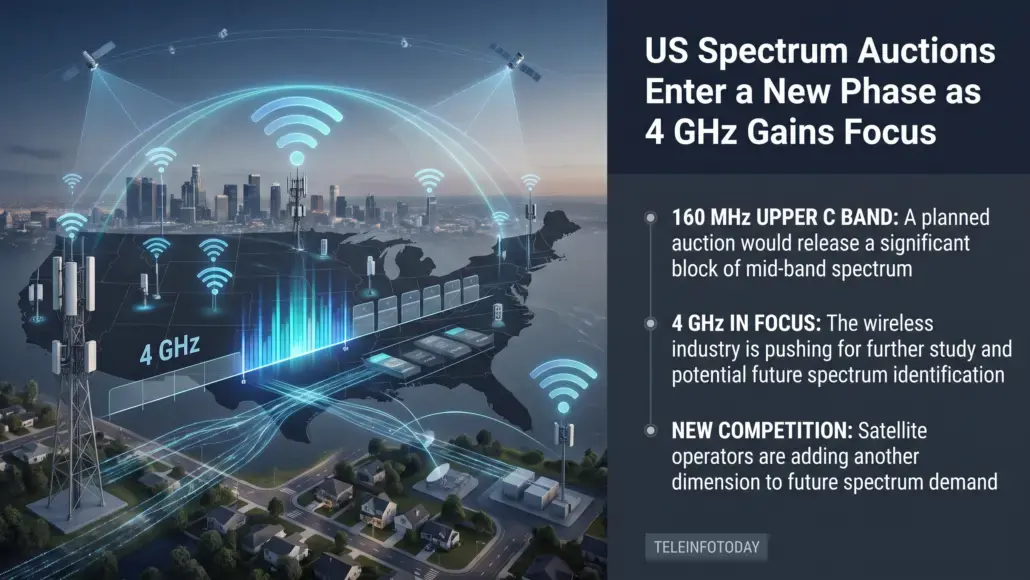
Carr outlined plans for an Upper C Band auction covering 160 MHz of spectrum, a move that would represent one of the most significant mid-band spectrum releases in recent years. Beyond that initial sale, additional spectrum bands have been identified for future US spectrum auctions, signaling a broader effort to keep pace with growing wireless demand.
During the discussion, Carr referenced a potential aggregate figure of more than $100 billion that forthcoming auctions could generate. It is important to note that this is not a guaranteed revenue total or an official auction estimate but rather a potential figure discussed in the context of the overall auction pipeline. Past auctions have delivered substantial proceeds. The AWS 3 auction brought in approximately $45 billion, and the earlier lower C Band auction generated around $81 billion. These are completed auctions and are separate from the forthcoming sales now being planned.
New Competition and Growing Satellite Interest
The upcoming US spectrum auctions could also see a shift in the competitive dynamics of bidding. There is growing interest from satellite operators, including SpaceX, in acquiring spectrum. This emerging demand from non-traditional bidders could reshape how wireless spectrum is valued and allocated in future rounds, though it remains to be seen how this competition will play out at auction.
The involvement of satellite companies alongside established wireless carriers adds a layer of complexity to the FCC spectrum pipeline. For telecom operators planning network infrastructure investments and capacity upgrades, understanding these competitive forces will be essential.
The Industry Push on the 4 GHz Band
A significant portion of the discussion centered on the 4 GHz band, where the wireless industry is pressing for faster regulatory action. CTIA has argued that the band could support both wireless coverage expansion and capacity improvements, making it a valuable resource for next-generation connectivity.
Specifically, CTIA has called on the National Telecommunications and Information Administration to advance its study of the 4.4 GHz band. The industry group envisions a longer-term path that would lead to formal spectrum identification and, eventually, a dedicated FCC auction for the band. However, these remain industry recommendations at this stage, and regulatory processes would need to run their course before any auction could be scheduled.
For telecom operators and wireless infrastructure planners, the trajectory of US spectrum auctions over the coming years will directly shape network buildout strategies. The combination of the planned Upper C Band sale, the broader auction pipeline, and the potential opening of the 4 GHz band points to a period of significant activity in spectrum policy. How quickly these processes advance will determine the pace at which new wireless capacity becomes available to meet rising demand across the United States.